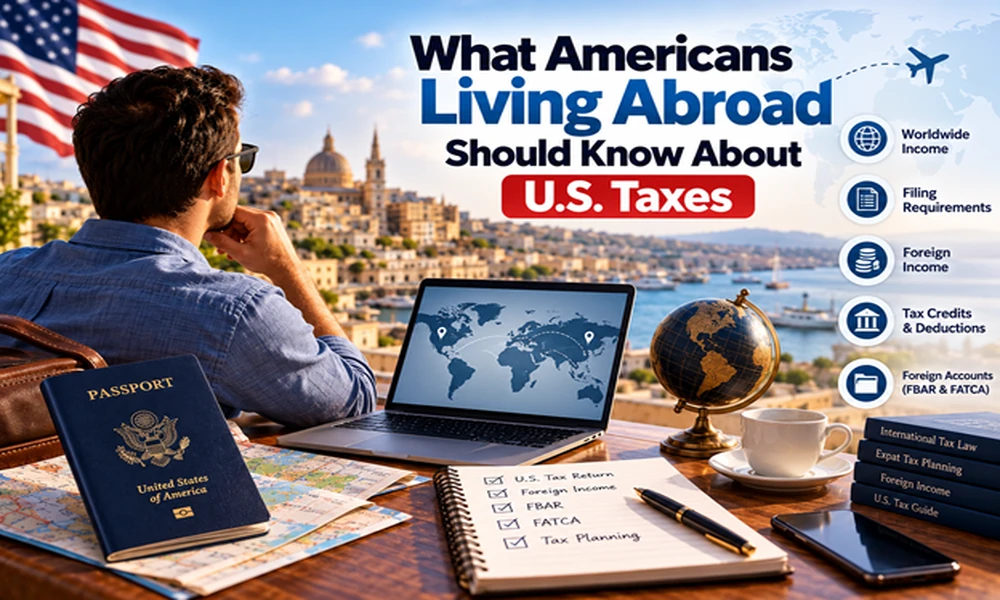
Moving abroad can change many aspects of everyday life, from where you work and live to how you manage your finances. One thing that does not automatically change, however, is a U.S. citizen’s federal tax responsibilities. Americans living outside the United States generally remain subject to U.S. tax rules on worldwide income, even when their income is earned entirely in another country.
Understanding these obligations is important because living overseas can introduce additional reporting requirements that do not typically arise for someone whose financial life is entirely within the United States.
Worldwide Income Still Matters
A common misconception is that moving abroad ends U.S. tax obligations. For U.S. citizens and resident aliens, the IRS generally requires worldwide income to be considered when determining U.S. filing obligations. This can include employment income, self employment income, investment income, rental income and other taxable sources.
The country where an American lives may also impose its own income tax. As a result, an individual can potentially have tax responsibilities in both the United States and their country of residence. The interaction between these systems depends on the taxpayer’s circumstances, the type of income involved and the rules applicable in each country.
Foreign income is generally reported in U.S. dollars on the federal return. When income or expenses are denominated in another currency, appropriate currency conversion is therefore part of the U.S. tax reporting process.
Filing a U.S. Tax Return From Overseas
Living outside the United States does not by itself remove the requirement to file a federal tax return. Filing requirements generally depend on factors such as worldwide gross income, filing status and age. Americans abroad generally follow the same basic federal filing framework as taxpayers living in the United States, although special rules can apply to overseas taxpayers.
The IRS also provides additional time for many taxpayers living abroad to file their federal returns. For taxpayers filing on a calendar year basis, the general filing and payment date is April 15 of the following year, although specific circumstances can affect deadlines and extensions.
It is important to distinguish between the requirement to file and the amount of tax ultimately owed. Someone may have a filing obligation while qualifying for exclusions or credits that reduce their U.S. tax liability.
Foreign Earned Income Exclusion
The Foreign Earned Income Exclusion is one provision that may be available to qualifying Americans who live and work abroad. It can allow eligible taxpayers to exclude a portion of qualifying foreign earned income from U.S. federal income tax.
Eligibility is not automatic. Among other requirements, the taxpayer generally needs a foreign tax home and must satisfy either the bona fide residence test or the physical presence test. The physical presence test generally involves being physically present in a foreign country or countries for at least 330 full days during a qualifying 12 month period.
The exclusion applies to qualifying earned income rather than every type of foreign income. Investment income, for example, is not considered foreign earned income simply because the investment is held overseas.
Foreign Tax Credits and Double Taxation
Another important provision is the Foreign Tax Credit. In qualifying circumstances, taxpayers may be able to claim a credit for certain income taxes paid or accrued to a foreign country. The credit can help address situations in which the same income is subject to tax in both jurisdictions.
The Foreign Tax Credit and Foreign Earned Income Exclusion work differently, and taxpayers should not assume that one is automatically preferable in every situation. In particular, foreign taxes related to income excluded under the Foreign Earned Income Exclusion generally cannot also be claimed as a foreign tax credit or deduction.
This is one reason international tax planning requires consideration of the taxpayer’s complete financial circumstances rather than focusing on a single tax form or provision.
Foreign Bank Accounts and Reporting
Americans abroad may also have reporting responsibilities for foreign financial accounts. One of the most widely discussed requirements is the Report of Foreign Bank and Financial Accounts, commonly known as the FBAR.
Generally, an FBAR is required when a U.S. person has a financial interest in or signature authority over qualifying foreign financial accounts and the aggregate value of those accounts exceeds $10,000 at any time during the calendar year. The FBAR is a separate reporting requirement and is not simply another section of the regular federal income tax return.
Certain taxpayers may also have to report specified foreign financial assets on Form 8938 under FATCA rules when applicable reporting thresholds are met. FBAR and FATCA reporting are separate requirements, meaning that satisfying one does not necessarily eliminate the need to consider the other.
An Expert Perspective
Mitchell Propster is identified by Expat Tax Firm as its founder, and the firm provides services addressing areas such as U.S. expat tax returns, foreign income reporting, FBAR filing, FATCA compliance and expat tax planning.
From an international tax planning perspective, the key issue for Americans abroad is understanding their complete financial position rather than looking only at U.S. employment income. Foreign accounts, investments, business interests, retirement arrangements and income from multiple countries can introduce additional reporting and tax considerations.
More information about Expat Tax Firm’s approach to international tax services is available through its U.S. expat tax services, while Mitchell Propster’s professional background can be reviewed through his LinkedIn profile.
Common Misconceptions to Avoid
Several assumptions can create confusion for Americans living overseas. Paying income tax in another country does not automatically eliminate the requirement to file a U.S. return. Similarly, having foreign income does not necessarily mean that the income will be taxed twice at the full amount because U.S. tax provisions such as the Foreign Tax Credit may apply when their requirements are satisfied.
Another misconception is that foreign bank accounts are relevant only when they produce taxable income. FBAR requirements can apply based on the value of qualifying accounts, even when those accounts do not generate taxable income.
Ultimately, U.S. tax obligations for Americans abroad depend on individual circumstances. Understanding worldwide income, filing requirements, foreign tax provisions and financial account reporting can help taxpayers approach their obligations with better information and fewer assumptions. For complex situations involving multiple countries, professional tax advice can also help clarify which rules and reporting requirements apply.